Best Business Travel Insurance Plans for International Corporate Trips
Managing corporate mobility across international borders requires navigating a complex intersection of duty of care obligations, enterprise risk transfer, and operational continuity. When executives, sales teams, or technical specialists deploy overseas, the exposure profile extends far beyond simple consumer inconveniences like delayed baggage or missed connection flights. An unaddressed medical emergency, a sudden geopolitical crisis requiring security extraction, or a lost laptop containing proprietary trade secrets can trigger severe balance-sheet liabilities, legal disputes, and reputational damage for an enterprise.
Corporate travel risk management demands an understanding of underwriting architecture, duty of care legal frameworks, primary versus secondary coverage triggers, and geographic compliance mandates. Standard personal travel insurance policies and baseline corporate credit card protections frequently collapse under the operational demands of international business trips. They embed low coverage caps, exclude high-risk commercial activities, enforce rigid named-peril definitions, and lack the direct-dispatch emergency assistance infrastructure required to support mobile workforces operating across diverse regulatory jurisdictions.
Evaluating protection frameworks for international business travel requires assessing specialized business equipment coverage, trip replacement riders, non-medical security extraction, emergency medical evacuation to tertiary care institutions, and corporate liability indemnification. As supply chain disruptions, health crises, and geopolitical realignments reshape international commerce, selecting appropriate corporate insurance policies demands a rigorous analytical framework.
Best Business Travel Insurance Plans for International Corporate Trips
To analyze the Best Business Travel Insurance Plans for International Corporate Trips, one must first decouple general consumer leisure travel protection from commercial risk management. In consumer markets, policies prioritize personal financial indemnity against pre-paid vacation losses. In enterprise risk management, corporate travel insurance serves as an operational risk transfer mechanism designed to fulfill legal duty of care obligations, protect intellectual property, maintain business continuity, and shield corporate capital from uncontrolled out-of-pocket liabilities.
A primary area of structural friction for enterprise risk officers is assuming that corporate credit card coverage or standard group health insurance delivers adequate protection for international business travel. Credit card benefits apply secondary coverage structures, require transactions to be processed on specific accounts, enforce low aggregate caps, and rarely provide business-specific protections like employee replacement riders or corporate equipment coverage. Domestic group health plans almost universally restrict foreign coverage to out-of-network emergency stabilization, leaving severe gaps in international medical transport, chronic condition management abroad, and direct hospital billing guarantees.
Furthermore, oversimplifying corporate policy selection by evaluating only headline per-policy limits introduces hidden operational vulnerabilities. A policy advertising $1,000,000 in emergency medical coverage may embed restrictive sub-limits—such as capping pre-existing condition waivers, restricting non-medical security evacuations to active war zones, or excluding non-scheduled commercial charter flights used for regional site visits. Evaluating enterprise protection balances overall financial caps against specific policy endorsements, global assistance desk capabilities, and underlying underwriter financial strength ratings.
Evolution and Context of Corporate Travel Risk
The structural evolution of corporate travel risk management spans three major operational eras, reflecting shifts in international labor law, global supply chains, and risk underwriting capabilities.
Before the 1990s, corporate travel protection operated reactively. Companies purchased ad hoc single-trip accident policies or relied on basic accidental death and dismemberment (AD&D) coverage. Policies operated on narrow named-peril frameworks that required specific events, such as catastrophic airframe accidents or severe commercial carrier insolvency, to trigger financial payouts.
The international expansion of multinational corporations in the late 1990s and 2000s highlighted the administrative and financial inefficiencies of transaction-based coverage. Insurers introduced Business Travel Accident (BTA) policies—blanket annual contracts covering all corporate travel departures. These policies pooled risk across an enterprise’s total travel footprint, offering streamlined administration, standardized coverage limits, and basic emergency medical assistance.
The contemporary business environment has expanded corporate risk profiles significantly. Landmark legal rulings establishing enterprise “Duty of Care” mandates require employers to take active steps to protect traveling staff from foreseeable physical, environmental, and geopolitical hazards. Modern corporate travel insurance has evolved from a financial reimbursement mechanism into an integrated logistics framework, incorporating real-time security tracking, political extraction capabilities, specialized cyber and equipment coverage, and comprehensive medical repatriation systems.
Key Categories of Business Travel Policy Architecture
Corporate travel insurance is not underwritten on uniform contract templates. Insurers structure products into distinct categories based on enterprise size, travel frequency, geographic exposure, and industry sector.
Blanket Annual Business Travel Accident (BTA) Policies
Blanket BTA plans serve as the foundation of corporate travel risk management. Rather than insuring individual trips, BTA policies automatically cover all employees traveling on authorized corporate business. Coverage applies automatically without requiring pre-trip registration, eliminating administrative failure points while maintaining standardized medical limits across the enterprise.
Group Multi-Trip Commercial Plans
Designed for medium-sized corporate fleets, these policies establish fixed per-trip duration caps (typically 30 to 60 days per departure) alongside specialized business equipment coverage. They provide cost-effective risk transfer for routine corporate travel across defined operational schedules.
Specialty Executive Protection Coverage
Tailored for C-suite officers and high-risk personnel, these policies feature elevated trip cancellation limits, political and security extraction capabilities, and hospital-of-choice evacuation protocols, offering high-level risk insulation during high-stakes international missions.
Commercial Business Equipment Riders
These endorsements extend policy limits past standard consumer baggage caps, insuring company-owned laptops, specialized diagnostic testing tools, prototype hardware, and trade show displays at full replacement value based on scheduled serial logs.
Real-World Scenarios and Decision Logic
Scenario 1: Specialized Technical Equipment Loss in Transit
A senior field technician travels from San Jose to Munich with $85,000 worth of specialized diagnostic hardware to repair a semiconductor manufacturing line. Commercial airlines cap baggage liability at statutory limits under international conventions, while standard personal policies embed low electronic caps. The enterprise requires a Corporate Business Equipment Endorsement attached to its BTA policy, scheduling the hardware by serial number to indemnify replacement costs and emergency freight shipping.
Scenario 2: Executive Medical Emergency in a Remote Zone
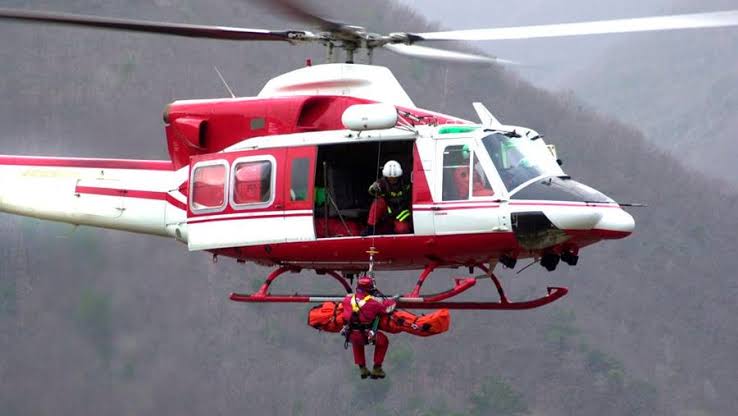
A corporate vice president visits a mining facility in remote South America and suffers severe cardiac distress. Local clinics lack cardiology units and intensive care infrastructure. Primary protection relies on a corporate BTA plan featuring a 24/7 Global Assistance Desk with direct-dispatch air ambulance authority and explicit hospital-of-choice repatriation terms, authorizing immediate air transport to a tertiary medical center.
Risk Landscape, Policy Friction Points, and Failure Modes
Managing corporate travel risk introduces complex legal, operational, and financial exposures. Understanding common failure modes prevents catastrophic coverage gaps during loss events.
-
The Off-Platform Booking Gap: Employees booking travel outside approved corporate management tools create visibility risks. Blanket annual BTA policies mitigate this vulnerability by covering all authorized business travel regardless of booking channel.
-
Hazardous Work Activity Exclusions: Standard policies cover executive, managerial, and professional duties. Dispatched technical staff performing manual labor or hardware maintenance require specialized Hazardous Occupations Endorsements.
-
Delayed Assistance Desk Notification: Arranging private medical evacuation without prior Assistance Desk authorization can lead underwriters to deny reimbursement, leaving the employer liable for transport costs.
Governance, Program Audits, and Strategy
Maintaining a compliant corporate travel protection framework demands structured program oversight, regular policy audits, and clear governance workflows.
-
Audit Travel Booking Data: Reconcile annual Travel Management Company booking logs against insurance underwriter reporting to ensure complete traveler day coverage.
-
Review Policy Coverage Caps: Evaluate emergency medical and evacuation limits against international healthcare inflation rates to confirm policy adequacy.
-
Confirm Duty of Care Compliance: Verify that corporate travel policies meet expanding legal requirements across all operating jurisdictions.
Conclusion and Strategic Synthesis
Selecting the Best Business Travel Insurance Plans for International Corporate Trips demands a structured analytical framework focused on enterprise risk exposure, legal duty of care mandates, primary coverage architecture, and operational continuity requirements. Surface-level evaluations based on low upfront premiums or baseline credit card perks fail to account for the financial liabilities of international medical emergencies, security extractions, or project disruptions.
By implementing blanket Business Travel Accident policies, securing primary medical and hospital-of-choice evacuation coverage, integrating real-time travel tracking systems, and conducting regular risk audits, corporate risk officers can establish a resilient travel risk management framework. Aligning travel protection with enterprise mobility goals shields corporate capital, protects human assets, and fulfills duty of care obligations across international operations.