Top Luxury Travel Insurance Policies for High-Value Trips
The financial risk landscape for high-value travel has shifted dramatically from routine trip delays toward complex, high-exposure liabilities. When an itinerary involves six-figure non-refundable deposits, private charter position fees, remote island transfers, or multi-jurisdictional medical evacuations, standard commercial travel insurance policies collapse under strict coverage limits, narrow named perils, and rigid claim definitions. For high-net-worth individuals, corporate executive desks, and family offices, securing adequate protection requires treating travel insurance not as an impulse add-on at checkout, but as a specialized risk management framework.
Navigating high-value travel protection demands an understanding of underwriting architecture, primary versus secondary coverage layers, sub-limits, and legal exclusions. A basic policy capped at $10,000 in trip cancellation coverage delivers zero protection for a $150,000 luxury safari or an Antarctic expedition charter. Furthermore, standard policies frequently exclude high-risk luxury activities, fail to cover private aviation mechanical disruptions, and limit emergency medical evacuations to the nearest acceptable facility rather than repatriating the patient directly to a trusted medical institution in their home country.
Evaluating protection for high-value itineraries requires assessing dynamic peril triggers, such as Cancel For Any Reason (CFAR) riders, non-medical security evacuations, concierge rescue services, and high-limit medical evacuation coverages. As global political instability, extreme climate events, and private charter logistics introduce unprecedented volatility into international travel, selecting the right underwriter demands a rigorous, multi-layered analytical framework.
Top Luxury Travel Insurance Policies for High-Value Trips
To evaluate the Top Luxury Travel Insurance Policies for High-Value Trips, one must first decouple standard consumer travel protection from high-net-worth risk underwriting. In mass-market travel insurance, policies are designed around statistically predictable, low-dollar claims—such as lost baggage, minor flight delays, or basic emergency room visits. In luxury travel risk management, coverage must absorb catastrophic non-refundable financial losses, complex intermodal transit delays, and multi-million-dollar medical logistics.
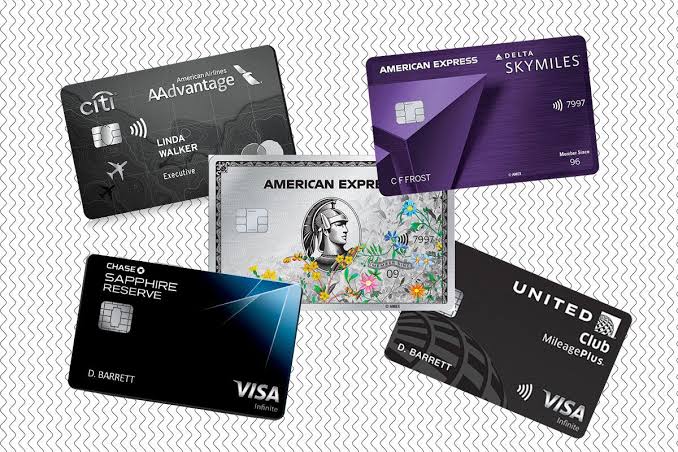
A common misunderstanding among luxury travelers is assuming that premium credit card travel protections provide sufficient coverage for high-value itineraries. While high-tier credit cards offer valuable baseline perks, their trip cancellation benefits almost universally cap payouts between $10,000 and $20,000 per trip or per year. For an itinerary featuring $100,000 in prepaid non-refundable resort deposits and private villa rentals, relying solely on card-based protection leaves over 80 percent of the financial asset completely exposed to loss.
Furthermore, oversimplifying high-value policy selection by focusing strictly on total policy caps introduces hidden operational traps. A policy advertising $1,000,000 in emergency medical coverage may embed severe sub-limits—such as capping search and rescue at $50,000, limiting pre-existing condition look-back waivers to 14 days post-deposit, or excluding non-scheduled charter aircraft flights. A rigorous evaluation framework balances headline coverage limits against specific policy endorsements, operational dispatch capabilities, and carrier financial strength ratings.
Evolution and Context of High-Value Travel Underwriting
The commercial travel insurance sector emerged in the mid-20th century, primarily providing basic accidental death and dismemberment coverage for commercial airline passengers. Early policies were transaction-based and rigid, operating on fixed named-peril structures that required specific, narrow events to trigger a payout.
As global wealth expanded and ultra-luxury travel evolved to encompass private island rentals, polar expeditions, non-scheduled charter flights, and extended multi-country sabbaticals, standard insurance products proved inadequate. Underwriters faced high-exposure claims where single travel disruptions generated losses exceeding several hundred thousand dollars. This operational gap led to the rise of specialty underwriting syndicates and high-net-worth personal lines insurers developing tailored luxury travel protection protocols.
Modern luxury travel insurance operates within a complex global environment. The contemporary landscape features heightened volatility in air traffic management, shifting climate patterns affecting remote destinations, and rapid geopolitical changes. Today’s high-value policies are designed around dynamic risk mitigation: incorporating real-time security tracking apps, direct-dispatch medical evacuation aircraft, and broad Cancel For Any Reason endorsements that decouple claim validity from specific named perils.
Key Categories of High-Value Policy Architecture
Understanding high-value protection requires categorizing policies by their structural mechanics, underwriting delivery methods, and operational scope.
High-Limit Standalone Comprehensive Policies
These standalone products cater specifically to high-value travel, offering single-trip cancellation caps ranging from $50,000 to $500,000 or more per insured individual. Underwritten by specialty insurers, these plans cover non-refundable deposits, private villa rentals, cruise bookings, and multi-leg luxury transfers under broad named perils. Premiums are scaled directly to traveler age and total insured cost, typically representing 6 to 12 percent of the non-refundable outlay.
Cancel For Any Reason (CFAR) Endorsements
CFAR is an optional rider attached to comprehensive policies that expands protection beyond standard named perils. It allows the policyholder to cancel an itinerary for any reason whatsoever—ranging from business conflicts to personal preference—typically returning 50 to 75 percent of non-refundable prepaid costs. It must be purchased within a strict window, usually 10 to 21 days from the initial trip deposit.
Dedicated Medical Evacuation Memberships
Standalone medical evacuation subscriptions operate independently from traditional travel insurance policies. Rather than reimbursing cash expenses, these programs dispatch certified air ambulances and medical personnel to transport hospitalized members home. These memberships cover medical transport and field rescue only, providing zero financial reimbursement for canceled flights or lost deposits.
Private Aviation and Charter Interruption Riders
Specialized endorsements designed to protect travelers utilizing non-scheduled charter aircraft or fractional jet cards. These riders reimburse secondary charter positioning fees, unexpected Aircraft On Ground replacement charter costs, and non-refundable resort stays lost due to private aircraft mechanical grounding.
Real-World Scenarios and Decision Logic
Scenario 1: Private Charter African Safari Logistics
A family of four undertakes a $180,000 multi-week private safari involving non-refundable lodge deposits and bush-plane charter hops. Remote bush-plane transfers operate outside commercial airline schedules, and lodges enforce strict non-refundable cancellation terms. The client requires a standalone specialty policy underwritten for $180,000 total exposure, incorporating a 75 percent CFAR rider, non-scheduled aircraft coverage, and a pre-existing condition waiver secured within 14 days of initial deposit. Relying on standard card coverage leaves $160,000 exposed to loss.
Scenario 2: Remote Polar Expedition Medical Evacuation
A couple joins an ultra-luxury icebreaker expedition costing $90,000. Remote sub-Antarctic waters pose extreme weather risks and limited shipboard medical care. Evacuation to home-country tertiary care facilities can exceed $250,000. Primary protection relies on a dedicated medical evacuation membership providing high-limit field rescue and transport paired with a hospital-of-choice clause, avoiding diversions to inadequate regional clinics.
Planning, Cost Dynamics, and Policy Pricing Structure
Understanding high-value policy pricing requires analyzing baseline actuarial variables, optional endorsement surcharges, and direct versus indirect financial inputs.
Actuarial base premiums are calculated primarily on traveler age and total non-refundable trip cost. Premium ratios scale non-linearly for travelers over age 65 or for itineraries exceeding $100,000. Adding a Cancel For Any Reason rider typically increases the baseline policy premium by 40 to 60 percent.
For example, an annual executive plan with a $10,000 per-trip cancellation cap typically carries an annual cost between $900 and $1,800. A standalone high-limit policy for a $50,000 trip costs between $2,500 and $4,200, while insuring a $100,000 trip with CFAR pushes premiums to between $7,000 and $11,500. Insuring an ultra-luxury $250,000 itinerary can require premiums from $18,000 to over $32,000 depending on traveler age and destination risks.
Delaying policy purchase past initial deposit windows forfeits pre-existing condition waivers and financial default coverage for travel suppliers, introducing severe financial opportunity costs.
Risk Landscape, Policy Friction Points, and Failure Modes
High-value travel insurance policies feature complex contractual mechanisms. Understanding common failure modes prevents catastrophic coverage gaps during loss events.
A common failure point is the pre-existing condition look-back trap. Standard policies exclude coverage for conditions treated or diagnosed within a 60- to 180-day window before policy purchase. Failing to purchase insurance within the initial deposit window forfeits the pre-existing condition waiver. If a traveler experiences a recurrence of a stable condition months later, the insurer can deny a high-dollar cancellation claim.
Another major breakdown occurs during unauthorized private medical extractions. Family members who independently hire a private air ambulance without prior authorization from the insurer’s Assistance Desk face complete claim denial, absorbing hundreds of thousands of dollars in out-of-pocket costs.
Conclusion and Strategic Synthesis
Selecting the Top Luxury Travel Insurance Policies for High-Value Trips requires a disciplined, analytical approach focused on structural contract terms, underwriting limits, operational dispatch capabilities, and precise policy layering. Relying on baseline credit card perks or generic mass-market policies leaves six-figure travel assets exposed to financial loss.
By evaluating risks through formal decision frameworks, securing policies within early deposit windows, requiring hospital-of-choice evacuation protocols, and keeping detailed documentation, travelers can mitigate high-exposure financial and medical risks. Aligning coverage parameters with personal travel patterns turns travel insurance into an effective risk management asset that preserves capital and ensures operational continuity anywhere in the world.