Top Adventure Travel Insurance for Hiking and Extreme Sports
Standard travel insurance is engineered around a statistically predictable set of urban and transit vulnerabilities: delayed commercial flights, misplaced baggage, minor illness in municipal medical facilities, or trip cancellation due to documented bereavement. The underwriting mathematics for these policies rely on high-volume, low-severity claims within controlled environments. When a traveler moves beyond urban infrastructure into high-altitude alpine terrain, remote backcountry corridors, or offshore marine environments, these standard actuarial models break down completely.
Navigating extreme environments shifts the risk profile from financial inconvenience to life-safety logistics. In backcountry environments, medical care is defined not by access to a local hospital, but by the physical feasibility of search and rescue operations, the availability of specialized rotary-wing aircraft rated for high-altitude operations, and international political clearances for cross-border medical repatriation. A standard policy’s fine print frequently contains general activity exclusions for hazardous sports, technical climbing, or altitude limits that effectively void coverage the moment a trekker steps onto a glaciated path or exceeds 3,000 meters above sea level.
Evaluating insurance coverage for high-risk wilderness activities demands an analytical approach that treats insurance policy documents as complex legal contracts rather than simple financial products. Protecting assets and human life during extreme expeditions requires examining search and rescue dispatch authorizations, emergency medical evacuation limits, altitude thresholds, equipment loss provisions, and the precise definitions of covered activities. This guide provides a detailed analysis of the systemic evolution, conceptual models, policy structures, financial dynamics, and risk management protocols that govern extreme travel underwriting.
Top Adventure Travel Insurance for Hiking and Extreme Sports
Evaluating Top Adventure Travel Insurance for Hiking and Extreme Sports requires looking beyond consumer-facing promotional materials to analyze the underlying policy wordings, underwriting guidelines, and operational logistics. In standard consumer finance discourse, adventure insurance is often presented as a simple optional add-on or sports rider attached to a baseline travel insurance plan. In practice, genuine extreme activity coverage functions as a specialized combination of field rescue coordination, catastrophic medical insurance, international repatriation coverage, and specialized equipment protection.
A primary source of claim denials for outdoor enthusiasts is failing to recognize the legal distinction between Search and Rescue (SAR) coverage and Emergency Medical Evacuation coverage. Standard travel insurance policies, even those offering nominal medical evacuation limits, frequently require a traveler to be situated at a recognized road-accessible medical facility before evacuation coverage activates. They explicitly exclude the search, location, and extraction phases required to transport an injured hiker from a remote mountain pass or technical climbing pitch to a road-head or regional clinic.
Furthermore, evaluating policies strictly on baseline medical coverage limits creates dangerous blind spots. An insurance policy promising a $1,000,000 emergency medical benefit is functionally useless in a backcountry emergency if its activity exclusions clause disallows claims arising from mountaineering involving ropes or ice axes, un-guided backcountry skiing, or any activity conducted above 4,000 meters. A complete evaluation balances headline financial limits against specific activity inclusions, technical gear definitions, geographical boundaries, and the operational authority of the insurer’s emergency assistance provider.
Evolution and Context of Adventure Underwriting
The historical development of adventure travel insurance reflects broader shifts in mountaineering history, commercial wilderness guiding, global satellite communications, and specialized actuarial data collection.
During the late nineteenth and early twentieth centuries, the golden age of alpine exploration operated largely without formal insurance products. Early European alpine clubs created mutual-aid rescue funds financed through member dues. These early funds were designed to reimburse regional mountain guides and local volunteer rescue teams for expenses incurred while retrieving injured climbers. Coverage was regional, highly informal, and reliant on local community support.
As commercial adventure travel expanded rapidly in the late twentieth century—driven by commercial trekking in the Himalayas, commercial whitewater rafting in the Americas, and international scuba diving—traditional travel insurers attempted to adapt standard policies by adding broad activity exclusions to manage risk. Insurers lacked granular actuarial data on high-altitude sickness rates or technical climbing accident frequencies, leading them to classify all non-standard outdoor pursuits as uninsurable risks. Travelers seeking coverage were forced to rely on specialized alpine club memberships or expensive, custom commercial syndicates.
The modern era is defined by satellite technology integration, global logistics networks, and specialized underwriting platforms. Modern adventure coverage relies on real-time satellite communication integration, allowing immediate two-way communication between field teams, emergency dispatch centers, and underwriters. Specialized underwriters now utilize detailed activity classifications, allowing travelers to buy tailored policies that match specific technical ratings, elevation levels, and geographical zones.
Key Categories of Policy Architecture
Adventure travel insurance policies differ significantly in legal design, underlying underwriting structures, service delivery mechanisms, and coverage focus.
Comprehensive Travel and Adventure Plans
Integrated travel plans (such as World Nomads or Allianz with riders) combine trip cancellation, lost luggage, and sports coverage into an all-in-one package. They excel at managing general transit disruptions alongside recreational sports, though altitude limits are frequently capped at 6,000 meters.
Medical Evacuation and Field Rescue Services
Dedicated evacuation platforms (such as Global Rescue or Ripcord Rescue Travel Insurance) focus purely on search, rescue, and specialized air evacuation. They offer direct field extraction capabilities and high or uncapped limits, though they exclude standard trip cancellation or routine luggage coverage.
Alpine Club Mutuals and Specialized Expedition Policies
Member-based rescue funds provided by organizations like the Austrian or American Alpine Clubs deliver cost-effective technical climbing rescue coverage. For extreme high-altitude peaks above 7,000 meters, specialized expedition policies provide custom underwriting for technical gear, solo expeditions, and remote mountain zones.
Real-World Scenarios and Decision Logic
Scenario 1: High-Altitude Pulmonary Edema on a Remote Trek
A trekker on Nepal’s Manaslu Circuit develops acute High-Altitude Pulmonary Edema at an elevation of 4,800 meters, requiring immediate rotary-wing evacuation to Kathmandu. The traveler holds a policy with an explicit altitude rider covering non-technical trekking up to 6,000 meters. The satellite SOS beacon alerts the assistance center, which coordinates with a local helicopter operator in Kathmandu. Had the traveler purchased a standard travel policy with an unadjusted 3,000-meter altitude cap, the insurer would deny the helicopter charter fee, forcing local operators to demand cash guarantees before launching the aircraft.
Scenario 2: Technical Fracture during an Un-Guided Rock Climb
A climber suffers an open leg fracture while on a multi-pitch rock route in Patagonia, requiring technical rope extraction by a local mountain rescue team. The climber carries a dedicated field rescue membership that explicitly covers mountaineering involving technical rope systems. The assistance center authorizes payment directly to the regional rescue team and coordinates air ambulance transport home after initial surgical stabilization.
Planning, Cost Dynamics, and Capital Accounting
Budgeting for adventure travel insurance requires evaluating baseline premiums, specialized rider add-ons, deductible structures, and out-of-pocket field expenses.
-
Standard Travel Policy (No Add-Ons): Cost: $50 – $150 per trip. Altitude Limit: 2,500m – 3,000m. Features standard flight delays, lost luggage, and basic hospital care.
-
Comprehensive Travel Plan + Extreme Sports Rider: Cost: $150 – $400 per trip. Altitude Limit: Up to 6,000m. Features trekking, scuba diving, off-piste skiing, trip cancellation, and field rescue.
-
Dedicated Field Rescue & Evacuation Membership: Cost: $250 – $600 annually. Altitude Limit: Uncapped or up to 7,000m+. Features uncapped search and rescue, field-to-hospital medevac, and home repatriation.
-
Full Expedition & High-Altitude Policy: Cost: $800 – $2,500+ per expedition. Altitude Limit: Above 7,000m. Features technical climbing, specialized helicopter extraction, and high-altitude medical care.
Risk Landscape and Operational Failure Modes
Navigating adventure insurance requires understanding the complex fine print, exclusion clauses, and operational friction points that lead to denied claims.
-
The Search versus Evacuation Legal Trap: Insurers frequently deny helicopter claims if the policy wording covers Emergency Medical Evacuation but excludes Search and Rescue. If a helicopter spends hours searching for a lost hiker before transporting them, the traveler may remain personally liable for the search portion of the flight.
-
Unlicensed Operator Exclusion: Many policies contain clauses invalidating coverage if the traveler participates in extreme activities managed by an unlicensed or unaccredited local operator or trekking agency.
-
Pre-Authorization Protocols: Failing to contact the assistance center’s 24/7 hotline before initiating commercial helicopter evacuations can invalidate claims, except when immediate life-safety risks prevent communication.
Governance, Maintenance, and Strategy
For expedition leaders, family offices, and outdoor organizers, maintaining comprehensive insurance protection across dynamic travel itineraries requires ongoing oversight and policy review.
-
Audit Activity Definitions and Technical Limits: Cross-reference every planned activity against the policy’s explicit inclusion list, verifying that technical ratings, rope usage, and gear specifications match your itinerary.
-
Verify Maximum Altitude and Depth Caps: Ensure the policy’s elevation ceiling exceeds the highest point on your route (including potential detour passes) by at least 500 meters.
-
Confirm Upfront Direct-Pay Authorization: Confirm in writing that the assistance provider will issue direct payment guarantees to local helicopter operators and hospitals, avoiding out-of-pocket payment demands.
Conclusion and Strategic Synthesis
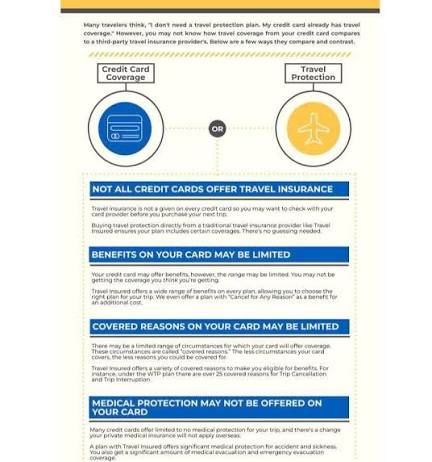
Selecting the Top Adventure Travel Insurance for Hiking and Extreme Sports requires a thorough, analytical review of policy contracts, operational logistics, activity exclusions, and evacuation capabilities. Relying on standard consumer travel policies or basic credit card coverage during backcountry expeditions introduces severe financial risk and operational vulnerabilities.
By systematically evaluating elevation caps, technical activity inclusions, search and rescue parameters, and the dispatch authority of assistance providers, travelers and expedition leaders can build a robust safety net. Through diligent planning, satellite integration, and careful policy selection, outdoor enthusiasts can navigate extreme environments with the confidence that their safety, health, and financial security are protected.