Top Travel Medical Insurance Plans for Senior Travelers
International travel for aging demographics represents one of the most complex intersections of public health policy, private financial underwriting, and global clinical logistics. As retirees and senior travelers cross international borders with greater frequency, longer trip durations, and higher medical complexity, the traditional mechanisms designed to protect consumer mobility face severe strain. Standard domestic healthcare infrastructure is inherently tied to territorial boundaries. The moment a senior traveler steps onto an international flight or boards a cruise ship operating in international waters, their primary domestic health coverage—whether U.S. Medicare, national health systems, or private managed care networks—often ceases to function or collapses into severe out-of-pocket exposure.
Underwriting travel medical risk for senior cohorts demands a distinct actuarial approach compared to younger traveler demographics. For younger travelers, risk models center on high-frequency, low-severity traumatic events or acute infectious illnesses. For senior travelers, the medical risk profile shifts dramatically toward acute exacerbations of chronic underlying conditions, complex cardiovascular events, orthopedic emergencies, and multi-system medical complications. These emergencies frequently require intensive care management, specialized transport logistics, and immediate guarantee of payment before international facilities will initiate definitive treatment.
Evaluating travel medical insurance for seniors requires moving beyond promotional literature to analyze policy contracts as rigorous legal documents. Protecting personal wealth and ensuring access to quality medical care abroad requires examining pre-existing condition exclusions, lookback periods, primary versus secondary coverage designations, emergency medical evacuation dispatch authorities, and age-banded premium escalations. This analysis breaks down the historical evolution, conceptual frameworks, policy variations, financial mechanics, and operational risk mitigation strategies that define senior travel health insurance.
Top Travel Medical Insurance Plans for Senior Travelers
When evaluating the Top Travel Medical Insurance Plans for Senior Travelers, one must first decouple standard travel protection from specialized travel medical insurance. Consumer travel insurance is largely structured around trip cancellation, flight interruptions, and baggage loss. While these benefits provide financial protection for prepaid travel costs, they often bundle nominal medical coverage that proves insufficient during major health crises overseas. In contrast, specialized travel medical plans operate primarily as emergency health policies designed to absorb massive clinical expenses, direct-pay hospital guarantees, and air ambulance repatriations.
A primary source of confusion for senior travelers is the false assumption that primary domestic health coverage extends across international borders. In the United States, original Medicare Parts A and B provide virtually no coverage outside the fifty states and territories, subject to extremely narrow geographic exceptions along international land borders. While select Medicare Advantage or Medigap supplemental plans offer emergency foreign travel benefits, these benefits are subject to lifetime caps, require high out-of-pocket deductibles, operate on a reimbursement basis, and carry steep co-insurance burdens.
Furthermore, evaluating policies strictly by their headline policy maximums can create a false sense of security. Insurance contracts contain age-tiered reductions that automatically reduce maximum benefit caps once an insured individual passes milestone ages, such as 70, 75, or 80. A plan advertised with a $1,000,000 policy maximum for a younger traveler may automatically drop to $50,000 or $10,000 for an older traveler, precisely when the statistical likelihood of requiring high-acuity medical care reaches its peak. Evaluating top-tier plans requires aligning policy terms with the traveler’s precise age band, destination infrastructure, and health profile.
Evolution and Context of Senior Risk Exposure
The structural evolution of senior travel health insurance reflects shifts in demographic longevity, global healthcare cost inflation, and international border regulations. During the late twentieth century, international travel among individuals over age 65 represented a small segment of total passenger traffic. Insurance products catering to this group were rudimentary, often featuring strict age ceilings that denied coverage altogether to travelers over age 70.
As global health outcomes improved and retirement dynamics evolved, international travel among seniors expanded significantly. Older travelers began engaging in longer, more complex itineraries, including multi-month winter relocations, long-haul cruises, and eco-tourism expeditions. Insurance underwriters recognized that blanket age exclusions were commercially unviable. However, the financial exposure associated with treating complex medical emergencies in foreign private hospitals required the development of sophisticated actuarial modeling.
The modern era is defined by dynamic risk management, direct-pay international hospital networks, and clear pre-existing condition waivers. Modern plans offered by specialized underwriters utilize detailed risk profiling, explicit waivers for pre-existing conditions, direct payment guarantees to international facilities, and 24/7 medical evacuation dispatch platforms.
Key Categories of Senior Policy Architecture
Travel medical policies for older adults differ across corporate underwriter networks, primary benefit structures, age limitations, and operational features.
Standalone Travel Medical Plans
Designed for travelers who prioritize health coverage over trip cancellation risks, standalone medical plans deliver substantial emergency medical coverage limits at a fraction of the cost of comprehensive plans. Backed by major medical networks, they facilitate direct payment to hospitals worldwide, eliminating the need for upfront cash payments.
Comprehensive Travel and Medical Bundles
Bundled policies protect both the financial investment in the trip and health risks abroad. They are ideal for expensive, non-refundable itineraries like cruises or guided tours. To secure pre-existing condition waivers under these plans, senior travelers must carefully follow purchase timing rules, securing coverage within 14 to 21 days of making their initial trip payment.
Dedicated Medical Evacuation Memberships
Standard travel medical policies authorize air ambulance transfers only if local medical facilities are judged incapable of providing basic care. Dedicated evacuation memberships bypass this requirement, guaranteeing air transport to an insured individual’s home hospital of choice once they are stabilized, regardless of local hospital adequacy.
Real-World Scenarios and Decision Logic
Scenario 1: Acute Cardiovascular Event on an European River Cruise
A traveler on a river cruise experiences severe chest pain, requiring emergency transfer to an academic medical center for cardiac catheterization and stent placement. The traveler holds a primary travel medical policy with a pre-existing condition waiver and a substantial medical limit. The assistance desk contacts the hospital administration, issues a formal letter of guarantee, and pays the hospital directly upon discharge, preventing heavy out-of-pocket liabilities.
Scenario 2: Orthopedic Fracture and Extended Hospitalization
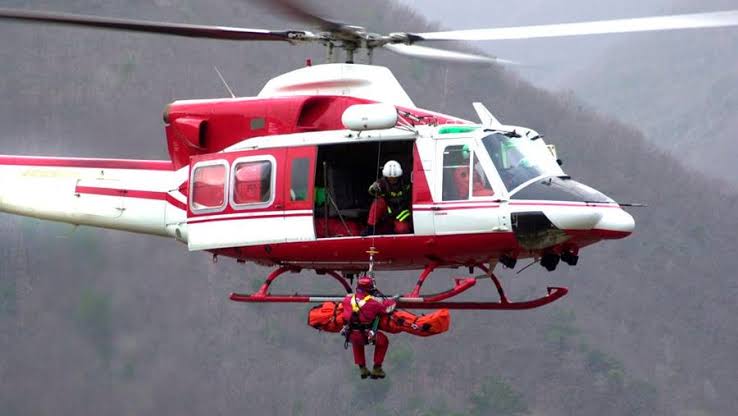
A senior traveler slips on uneven terrain abroad, sustaining a complex hip fracture requiring open reduction and internal fixation surgery. Because the regional hospital lacks specialized rehabilitation equipment, the assistance team arranges an air ambulance transfer to a high-acuity tertiary facility, followed by nurse-escorted commercial flight repatriation back to the home country.
Planning, Cost Dynamics, and Capital Accounting
Budgeting for senior travel medical insurance requires analyzing age-banded premium escalations, deductible selections, policy caps, and out-of-pocket financial risks.
-
Standalone Travel Medical (Ages 65–69): Estimated cost remains economical. Pre-existing waivers available via strict timing rules. Includes robust emergency medical evacuation benefits.
-
Standalone Travel Medical (Ages 75–79): Premiums adjust upward due to age risk profiling. Features high medical limits and direct-pay international hospital networks.
-
Comprehensive Trip & Medical Bundles (Ages 70–74): Moderate to high package pricing. Includes trip cancellation, interruption, baggage protection, and high-tier emergency health benefits.
-
Comprehensive Trip & Medical Bundles (Ages 80+): Highest premium tier reflecting statistical mortality and morbidity risks. Requires strict adherence to pre-existing condition waiver timelines.
Risk Landscape and Operational Failure Modes
Understanding policy exclusions, legal traps, and operational failure points helps prevent unexpected claim denials.
-
The Lookback Window Medication Adjustment Trap: If a physician adjusts a senior traveler’s blood pressure or cholesterol dosage during the 60 to 180-day lookback window, the insurer may classify any cardiovascular event during the trip as an excluded pre-existing condition unless a waiver was secured.
-
The Unapproved Evacuation Penalty: If family members independently arrange private medical transport or air ambulance services without prior written authorization from the insurance assistance desk, the insurer can deny coverage entirely.
-
Secondary Payer Delays: Utilizing secondary policies without understanding coordination-of-benefit rules can cause months of administrative delay while foreign hospitals demand immediate settlement.
Governance, Maintenance, and Strategy
For frequent travelers, adult children managing parent care, and family offices, maintaining proper travel medical coverage requires ongoing oversight and structured policy review.
-
Verify Policy Effective Dates and Age Limits: Confirm that the policy covers the entire trip duration and that age-tiered benefit reductions do not take effect mid-trip.
-
Confirm Pre-Existing Waiver Confirmation: Ensure the policy documentation explicitly confirms that the pre-existing condition waiver is active and valid.
-
Program Emergency Numbers into Mobile Devices: Store the international phone numbers and policy numbers for the insurer’s 24/7 emergency assistance desk prior to departure.
Conclusion and Strategic Synthesis
Selecting among the Top Travel Medical Insurance Plans for Senior Travelers requires an analytical framework focused on primary indemnity structures, direct-pay capabilities, clear pre-existing condition waivers, and reliable emergency medical evacuation dispatch authorities. Relying on basic credit card travel perks, domestic health insurance, or budget travel policies during international journeys creates substantial out-of-pocket exposure and operational risk.
By aligning policy choices with the traveler’s precise age band, purchasing coverage within the required deposit window, and verifying direct-pay networks before departure, senior travelers can protect their personal assets and ensure access to quality healthcare worldwide. Through careful contract analysis and proactive planning, travel medical insurance serves as an essential framework for safe, confident international travel.